
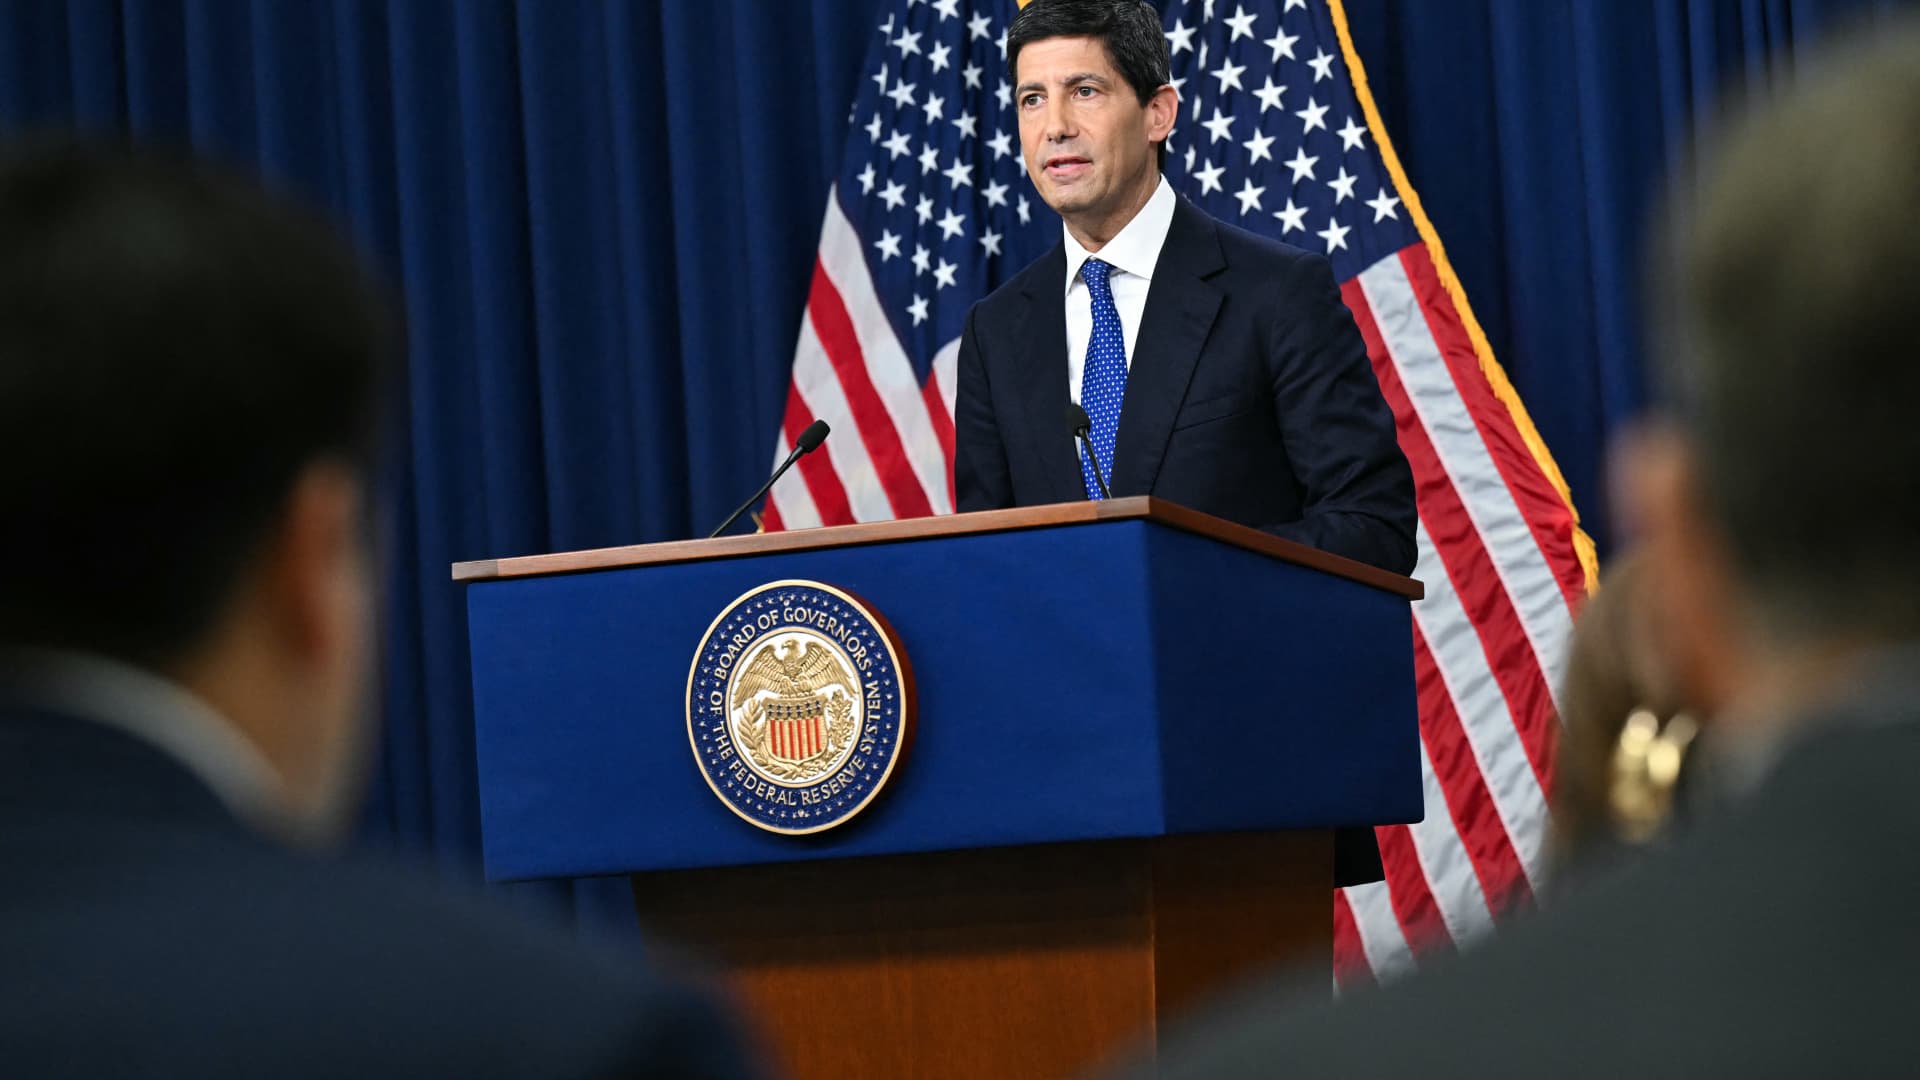
According to CNBC’s recent survey, nearly all economic analysts are predicting a pause in interest rate changes at the upcoming Federal Reserve meeting, which takes place this week. This survey, which included responses from 30 fund managers, strategists, and economists, indicated that a substantial 93% are in favor of maintaining current rates in October.
A majority of those surveyed—76%—expect a rate hike in December, with forecasts suggesting an additional two rate increases may occur next year. Richard Bernstein, head of macro investing at Janus Henderson Investors, expressed concerns about the Fed’s cautious approach, stating that after a lengthy period of monetary and fiscal support, prevalent economic indicators necessitate a reassessment of the current rates.
The survey revealed a strong belief that the Fed needs to dampen economic growth to combat inflation, with 40% of respondents asserting that growth must fall below potential to effectively address rising prices. In contrast, 27% argue that a slowdown isn’t necessary, while 23% suggest only a modest reduction is required.
Furthermore, 70% of the respondents believe that the inflationary pressures extend beyond surging energy prices. Predictions for the U.S. crude oil benchmark project a rise from $82 to $88 per barrel over the next six months, although this remains lower than its current price of $101.
Amidst the debate over the Fed’s potential actions, 30% of respondents believe that immediate rate hikes are warranted. It is expected that at least two officials from the Federal Reserve may voice dissent regarding the decision to hold rates steady.
John Ryding, chief economic advisor for Brean Capital, underscored the urgency for rate increases, pointing to strong demand and inflation data as critical pressures on the Fed to take action. However, not all analysts agree. Mark Zandi, chief economist at Moody’s Analytics, highlighted concerns about a faltering economy, noting real wage declines and rising interest rates as significant factors that caution against additional hikes at this juncture.
Despite facing numerous economic challenges, including high inflation and anticipated Fed rate lifts, respondents project that economic growth will remain above potential. The growth forecast for GDP this year has improved slightly to 2.4%, with expectations of a decrease to 2.2% for 2027, and an estimate of 2.05% for 2025. The probability of entering a recession within the next year has eased slightly, down to 26% from 29% in the previous survey.
The outlook for the S&P 500 index remains stable at around 7,600 for the current year, though it has been adjusted downward for next year to approximately 8,033, in contrast to the previous forecast of 8,274. Unemployment rates are expected to hold steady at 4.2% for the remainder of this year but may edge up to 4.4% by 2027. The Consumer Price Index is projected to decrease to 3.6% from 3.7% in September, and further drop to 2.6% in the following year.
Respondents identified ongoing risks such as the escalation of the Iran conflict and potential instability within the artificial intelligence sector as significant concerns that could impact market dynamics. Rob Morgan, senior VP and market strategist at MOSAIC, urged that resolving international conflict and trade tariffs would be the most effective strategy for alleviating inflationary pressures.
When analyzing the causes behind elevated bond yields, survey participants were nearly evenly split, attributing rising yields to high inflation, robust growth, extensive government debt issuance, and the prospect of increased Federal Reserve rates. Approximately half of the respondents pinpointed government debt as a larger factor compared to debt incurred for funding AI advancements, while a third acknowledged that both elements contributed equally to the yield increases. On average, the 10-year yield is anticipated to remain above 5% for the year before slightly adjusting to 4.8% in 2027.
Political uncertainty leading up to the congressional elections is also viewed as a market risk. Sixty-three percent of respondents indicated concern over potential legal challenges that could prolong ambiguity regarding congressional control. A majority—over half—believe that Democrats will secure control of both houses, while 40% anticipate a scenario where Democrats hold the House but not the Senate.
Despite expectations of no significant tax changes post-election, 41% foresee an increase in deficits. Interestingly, individual growth predictions showed little variation based on the anticipated congressional outcomes.
