
In a recent interview with Channel 10, Israeli Prime Minister Benjamin Netanyahu mentioned the idea of an “alternative economic system” ahead of elections. This statement raises significant questions regarding the practical application of cryptocurrency in bypassing international sanctions.
Having observed the evolution of the cryptocurrency market since 2014 and currently collaborating with blockchain enterprises worldwide, I can offer insights into whether a nation can utilize cryptocurrency to circumvent sanctions. The reality is more complex.
The Concept of Cryptocurrency
The term “crypto” is somewhat outdated within the industry; terminology like blockchain or Web3 has gained prominence. Cryptocurrencies were designed as universal monetary systems that require only internet access for use. The implications of this are significant, particularly for individuals in regions with limited banking infrastructure. Over a billion people globally lack access to a bank account.
Bitcoin addresses this gap by providing equitable access to financial resources. Since Bitcoin’s inception, advancements in blockchain technology—such as Ethereum—have broadened the functionalities available to users, including lending and borrowing options. While many tokens, including popular meme coins like DOGE or FARTCOIN, exist, most hold little to no value.
Stablecoins, tokens pegged to the value of traditional currencies, create a seamless method for cross-border transactions. For instance, a designer in Brazil could quickly receive payment from a small business owner in Ukraine for commissioned work.
Transparency in Transactions
Cryptocurrency inherently operates on a transparent framework. The blockchain functions as a public ledger, preserving permanent records of transactions. This aspect complicates any potential strategies to evade sanctions, as authorities can trace transactions back to their sources.
For instance, the Israeli Defense Ministry recently placed sanctions on 37 crypto wallets linked to the IRGC and Hezbollah, amounting to over 24 million NIS. Tether, a leading issuer of US dollar stablecoins, has also frozen significant amounts ($344 million in April and $131 million in July) from accounts associated with Iran’s central bank.
In 2025, a significant $104 billion in cryptocurrency was reportedly received by sanctioned entities, an increase of eight times from the previous year, illustrating that while crypto may offer a workaround, it does not entirely escape the broader financial mechanisms in place.
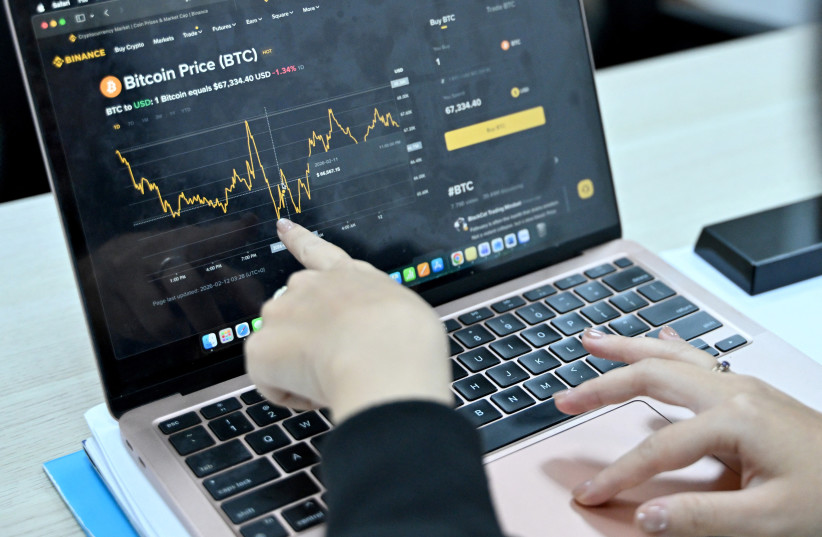
However, it’s essential to recognize that cryptocurrency’s role in the economies of nations facing sanctions is minimal compared to their overall economies. Most financial activities continue to rely on traditional banking systems, with components like salaries and loans primarily processed through banks.
The notion that a country like Israel could solely pivot to a crypto-based economy due to sanctions is unrealistic. Effective sanctions are typically designed to sever ties with trading partners, negating the benefits that could be derived from adopting cryptocurrencies.
The Bank of Israel underscored this point, stating, “Cryptocurrencies cannot serve as a means of circumventing sanctions… what is right for Israel’s economy is to preserve our economic relations with our main trading partners.” The notion of a crypto-based escape route could introduce more complications than benefits.
Integrating Cryptocurrency Properly
Nevertheless, this does not imply that countries should shy away from cryptocurrency altogether. Instead, it is crucial to incorporate it responsibly within established financial systems. For instance, the United States has begun enacting laws around stable currencies, exemplified by the GENIUS Act.
European regions have also responded positively; MiCA legislation facilitates crypto operations across Europe. Cities like Hong Kong and Singapore have implemented frameworks that encourage, rather than discourage, the industry. The goal is to integrate cryptocurrencies into the financial landscape rather than treat them as a means of escape from regulations.
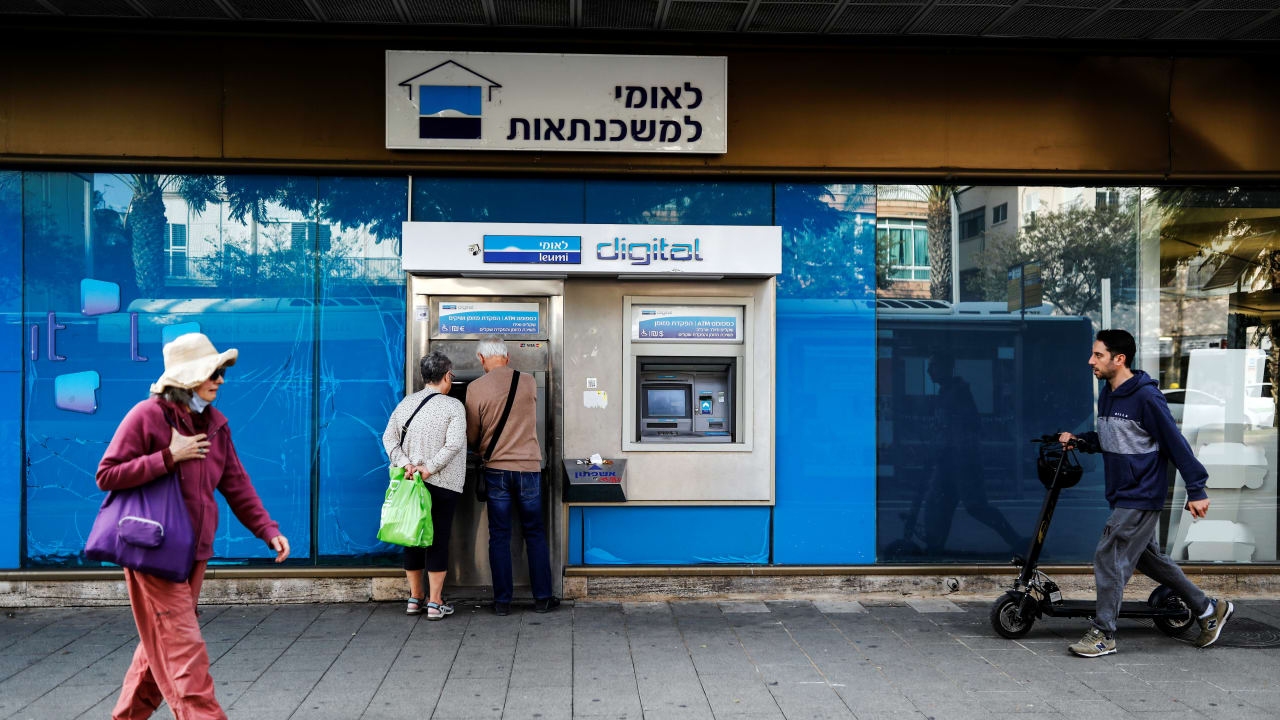
Israel is making progress along this path, contrary to the implications made by Netanyahu. The country recently approved its inaugural regulated shekel-pegged stablecoin and is exploring the introduction of a digital shekel. Additionally, institutions like Bank Leumi are preparing to facilitate Bitcoin transactions for their clients.
Despite the challenges, Israel possesses a highly intelligent workforce, along with a thriving tech startup culture underpinning the blockchain sector. Companies like Fireblocks, which provide security solutions for digital assets, and Bancor, a pioneer in decentralized finance, highlight the nation’s advancements in the crypto space. Furthermore, Israeli experts are highly regarded for their capabilities in tracing illicit crypto activities, which further complicates any plans to bypass financial restrictions using cryptocurrencies.
Economic data reflects potential in the field; Israeli web3 companies attracted $405 million in 2024, as reported by KPMG, though a recent analysis highlighted a 12% workforce reduction due to challenges in the operational landscape.
A primary barrier for progress in this sphere has been banking institutions. Historically, Israeli banks have resisted accepting funds derived from cryptocurrency activities. However, the Bank of Israel recently mandated that banks cannot reject funds sourced from crypto platforms, marking a positive shift.
In summary, Israel exemplifies the potential for mainstreaming cryptocurrency as part of the global financial system, enabling quick transactions and efficiency in retail and service sectors. A streamlined regulatory framework would foster domestic innovation rather than prompting companies to relocate to jurisdictions with more favorable conditions.
Ultimately, the leadership should advocate for responsible integration of cryptocurrency based on existing frameworks rather than vague notions of economic evasion. As Netanyahu stressed, a serious approach to the discussion of cryptocurrency is essential; however, it should be rooted in practicality.
The author serves as the chief client officer at MarketAcross, a PR and content agency located in Tel Aviv, specializing in blockchain communications. The views expressed here are solely those of the author.
