
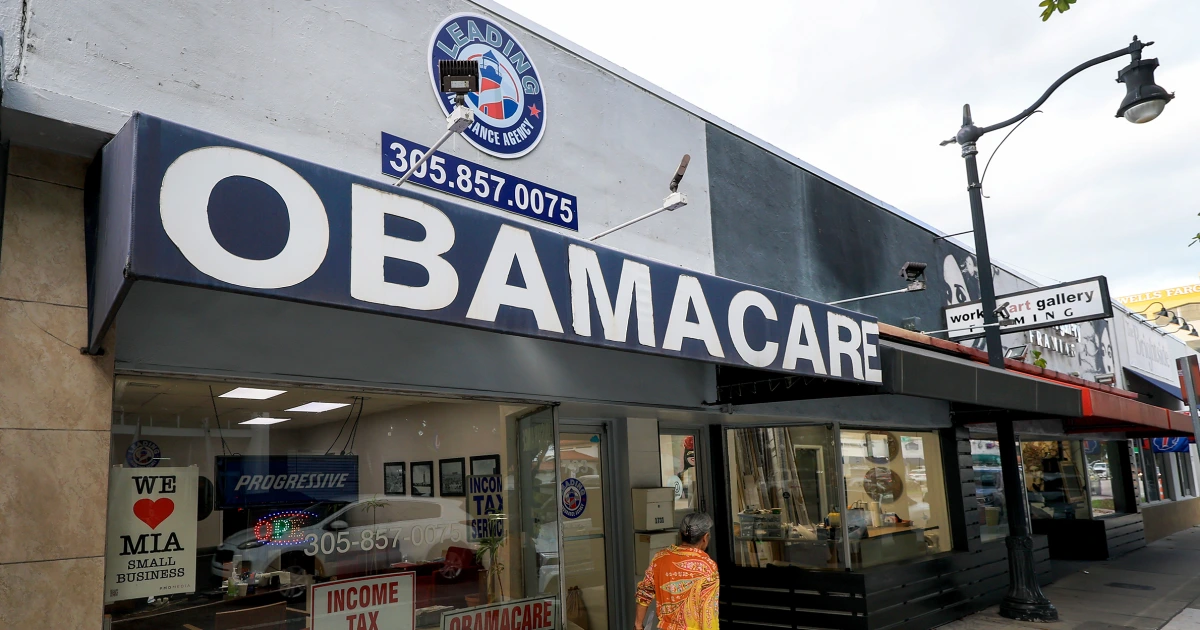
Health insurance consumers are bracing for a challenging open enrollment season in the Affordable Care Act (ACA) marketplaces, as many are faced with increased premiums and reduced options for coverage. Courtney Mroch from Nashville, Tennessee, is among those concerned about future insurance availability and costs.
Currently, Mroch pays $1,250 monthly for a silver healthcare plan, which is a substantial rise from the $850 she paid in 2025. With a history of diabetes, asthma, and cancer survivorship, she finds herself in a precarious position as she contemplates what her insurance landscape will look like in 2027. “Who knows who will cover me in 2027 or how much more it’ll cost?” she expressed.
The ACA open enrollment period begins this Sunday, offering approximately two months for Americans to compare insurance plans. However, many will encounter the stark reality of average premium increases of about 15% for 2027, marking the second consecutive year of double-digit hikes, according to analysis from KFF, a nonpartisan health policy research organization.
Simultaneously, a challenging trend is emerging: 11 insurers, including Cigna, are set to exit the ACA marketplaces in numerous states, significantly impacting consumer choices. Cigna alone plans to withdraw from all 11 states in which it currently offers plans, affecting over 350,000 enrollees. Although some insurers are entering new markets, the net effect leaves consumers with fewer choices overall.
“More insurance companies are leaving the marketplace than coming in,” noted Cynthia Cox, director of the ACA program at KFF. “This shift may lead to fewer insurers available and compel many individuals to switch plans.” This situation is particularly troubling for those with chronic illnesses who rely on consistent care from their selected providers.
Miranda Yaver, a health policy and management assistant professor at the University of Pittsburgh, said, “This will create significant disruptions in care and coverage for many individuals,” especially for those managing chronic health conditions. “If a patient’s physician does not accept the limited insurance options available, it can lead to serious disruptions in their care.”
Reasons Behind Insurer Withdrawals
The recent retreat from the ACA by these insurers can be attributed to the expiration of enhanced tax credits at the end of 2025. This led to a decline in ACA enrollment by approximately 3 million individuals, as healthier participants opted for cheaper and less comprehensive plans or dropped their coverage altogether. Those remaining in the ACA avenues typically have higher health needs and related costs, presenting a financial challenge for insurance providers.
Jennifer Chumbley Hogue, an insurance broker in Texas, highlighted this issue, saying, “Normal upheaval will occur due to changes in plans, subsidies, or doctor networks.” A spokesperson for Cigna reaffirmed that their departure from the ACA marketplace aligns with their goal of ensuring long-term sustainable growth for their core healthcare businesses.
Many families have already faced difficult financial choices due to rising premiums. In Colorado, Denise O’Connor and her husband saw their monthly premiums more than double from just over $900 to about $2,300. “We had to dip into our retirement savings,” she explained, while considering looking into alternative plans through a broker to ease the burden.
Similarly, in Idaho, Mark Lathrop and his wife are grappling with finding new coverage after their insurer, PacificSource, decided to exit the ACA marketplace. Without access to ACA subsidies, Lathrop anticipates a 2027 plan costing around $17,600, up from about $16,000 the previous year. Such increases in costs, combined with essential healthcare requirements, are raising uncertainties for many consumers.
According to a PacificSource spokesperson, the decision to exit the ACA marketplace was not made lightly and was intended to maintain their capacity to serve members effectively amidst growing pressures in the healthcare industry.
Experts like Yaver caution that these changes might weaken public support for the ACA as enrollment decreases and remaining participants face increased costs and fewer choices. The latest KFF poll indicated a drop in public favorability for the ACA from 64% to 58%, suggesting a shift in attitudes toward the program.
As consumers prepare for the open enrollment period, Hogue emphasized the importance of reevaluating insurance options rather than merely relying on mailed notifications. “The actual premiums and available subsidies may be different from what you see in those letters,” she advised.
In this period of uncertainty, individuals are encouraged to take proactive steps to assess their health coverage options to ensure comprehensive care aligned with their financial circumstances.
