
Recent reports from the Commerce Department have unveiled significant economic movements, indicating robust growth and persistent inflationary pressures in the U.S. economy. In the third quarter, the country’s gross domestic product (GDP) grew at an annualized rate of 3.4%, exceeding expectations and marking an uptick from the previous quarter’s 2.2% growth. This growth rate surpassed analysts’ forecasts of 3.1% and showcased resilience amid various economic challenges.
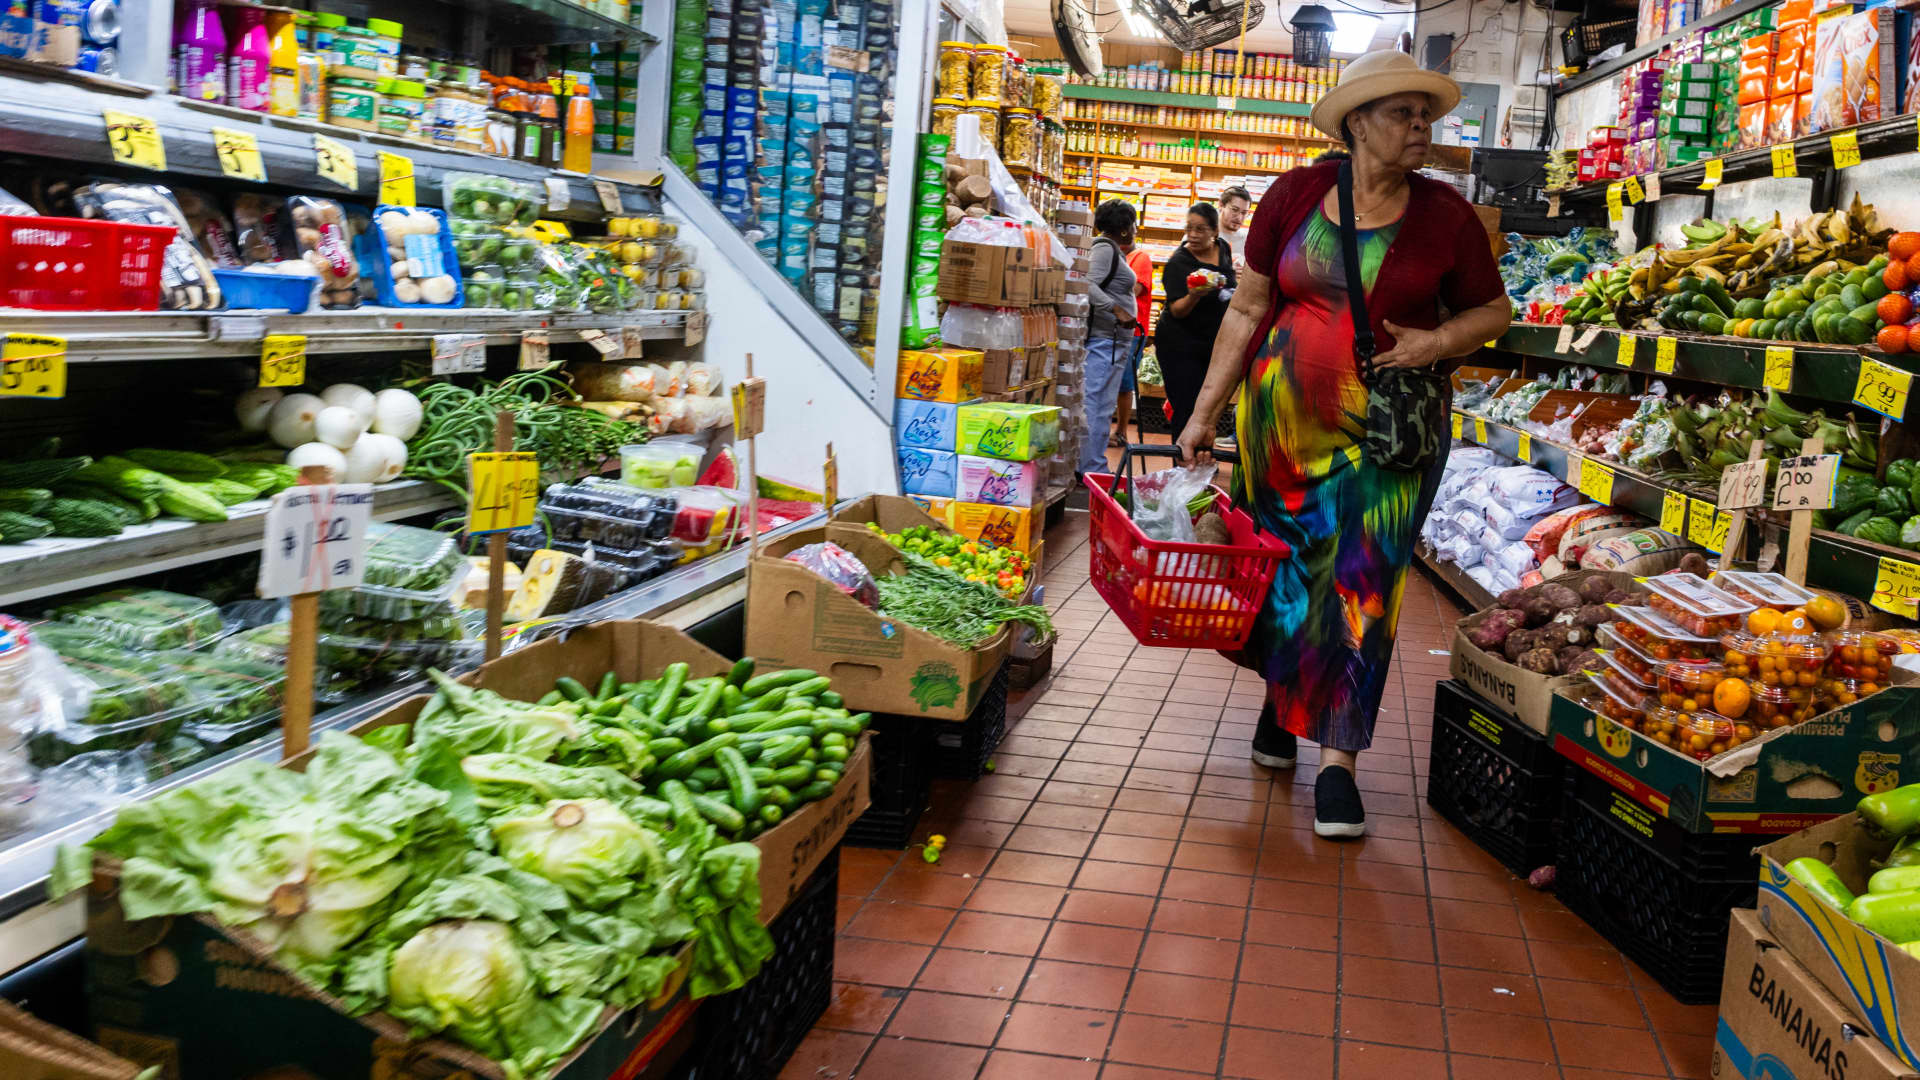
On the payments side, inflation has remained a pressing issue. In September, the personal consumption expenditures (PCE) price index rose by a seasonally adjusted 0.5%. This increase pushed the annual inflation rate to 3.6%, slightly below the Dow Jones consensus but still highlighting the ongoing challenge of rising prices. When excluding volatile food and energy sectors, core PCE reflected a monthly increase of 0.3% and an annual rate of 3.1%, aligning with expectations. This core measure is often regarded as a clearer indicator of long-term inflation trends by Federal Reserve officials.
Consumer expenditures demonstrated resilience as well, increasing by 0.5% in September, although this figure fell short of the anticipated 0.6% rise. Concurrently, personal incomes grew by 0.2%, which was less than the expected 0.3%. These figures emerged just a day after the Federal Reserve opted to maintain its benchmark interest rate in a range of 3.75% to 4%, emphasizing the importance of evaluating incoming data before making further adjustments amid ongoing inflationary concerns.
Federal Reserve officials have articulated a conscious awareness of the evolving economic landscape. Fed Chairman Kevin Warsh stated, “The period right in front of us is information rich. There is a lot that’s happening in the world. My colleagues and I are keen to take notice of it,” highlighting their cautious approach toward interest rate adjustments in light of fluctuating data.
In addition to the GDP and inflation statistics, labor market data released by the Labor Department revealed that initial jobless claims have dipped to a seasonally adjusted 194,000 for the week ending October 24, lower than the anticipated 200,000. This figure demonstrates sustained strength in the job market, which has remained resilient despite broader economic uncertainty.
Stock market futures reacted negatively to the economic reports, and Treasury yields experienced declines. Chris Rupkey, chief economist at Fwdbonds, stated, “Net, net, economic growth is powering ahead despite the uncertainty of geopolitical risks and the damage posed to many sectors of the economy by higher energy costs.” He noted that GDP has rebounded above a 3% growth rate for the first time in a year.
The third quarter’s economic growth can be attributed to increased investments, particularly in the artificial intelligence sector, alongside strong consumer and government spending. Consumer spending rose by 3.8% in the third quarter, mirroring the growth rate from the prior period. Gross private domestic investment surged by 19.4%, significantly supported by a remarkable 20.9% increase in equipment spending and an 8.4% rise in investments related to intellectual property products.
In terms of inflationary pressures, the PCE prices increased on a quarterly basis by 2.1% overall, with core prices rising by 2.5%. This marked a decrease from second quarter figures of 5% and 3.3%, respectively. However, September’s price hikes were largely driven by steep increases in energy costs. Economists expressed concern about the potential impact of these rising costs on other sectors of the economy, as gasoline and energy prices shot up by 9.2% and 5.4% respectively, with services prices (excluding energy and housing) increasing by 0.4% and housing costs rising by 0.3%.
