
A recent report indicates that the Federal Reserve may encounter challenges in justifying an interest rate hike amid persistent inflationary pressures. As statistics from the personal consumption expenditures (PCE) price index are set to be released, analysts anticipate increases of 0.3% at both the headline and core levels—parameters that exclude food and energy costs, according to Dow Jones projections.
The annual inflation rates are expected to remain elevated, with predictions of increases to 3.7% for all items and 3.3% for the core category, unchanged since July. These figures remain significantly above the Fed’s targeted inflation rate of 2%, suggesting no immediate relief from rising prices.
Dan North, a senior economist at Allianz Trade, stated, “The Fed is going to look at this and say, ‘Hey, you know, the core is not moving, and I don’t have any expectations or anything to believe that it’s going to start going back down in any sort of convincing way.’ It’s still way above target,” highlighting the potential for ongoing economic ramifications.
Outlook on Interest Rate Decisions
In their September meeting, Federal Reserve officials approved a 0.25 percentage point interest rate hike and have indicated the possibility of another increase by year-end. The majority of the eighteen members of the Federal Open Market Committee foresee at least one further adjustment in 2026, coupled with a revised outlook for PCE inflation.
Fed Chairman Kevin Warsh remarked earlier this month that the economy appears stable, citing strong hiring metrics, business investment, and company earnings. He noted, “I would be hard pressed to describe broad financial conditions as restrictive,” emphasizing the relevance of financial conditions in the Fed’s rate-setting approach.
Diverse Perspectives from Fed Officials
Fed Governor Michael Barr acknowledged external factors affecting inflation, stating that ongoing tariffs and the extended conflict with Iran have diverted progress towards achieving the 2% inflation goal. He expressed skepticism over the emergence of a clear trend toward this target in the near future.
“In my base case, further policy adjustments are likely to be needed to ensure inflation comes down to target in a timely fashion,” Barr mentioned, confirming the necessity for additional rate hikes, although he did not specify an exact figure. Currently, the Fed’s benchmark interest rate falls between 3.75% and 4%.
Conversely, New York Fed President John Williams identified another contributing factor to inflation: the demand for goods related to artificial intelligence. While he expressed some optimism about indicators suggesting housing services prices have moderated and the labor market is not exacerbating inflation, he still anticipates “one further upward adjustment” of rates may be necessary this year.
Consumer Spending Trends
The upcoming inflation data release also carries implications for consumer behavior, particularly against the backdrop of revised figures from the Bureau of Economic Analysis (BEA). The BEA is modifying its pricing methodology for specific services from 2021, potentially resulting in lower inflation readings for July by two or three tenths of a percentage point, allowing the 12-month figure to possibly dip to 3% based on various Wall Street estimates.
This adjustment might enhance the understanding of past trends without reorienting the future outlook, which remains uncertain. For instance, Goldman Sachs has indicated that upcoming inflation data could present “somewhat less favorable” results before a more favorable trend resumes.
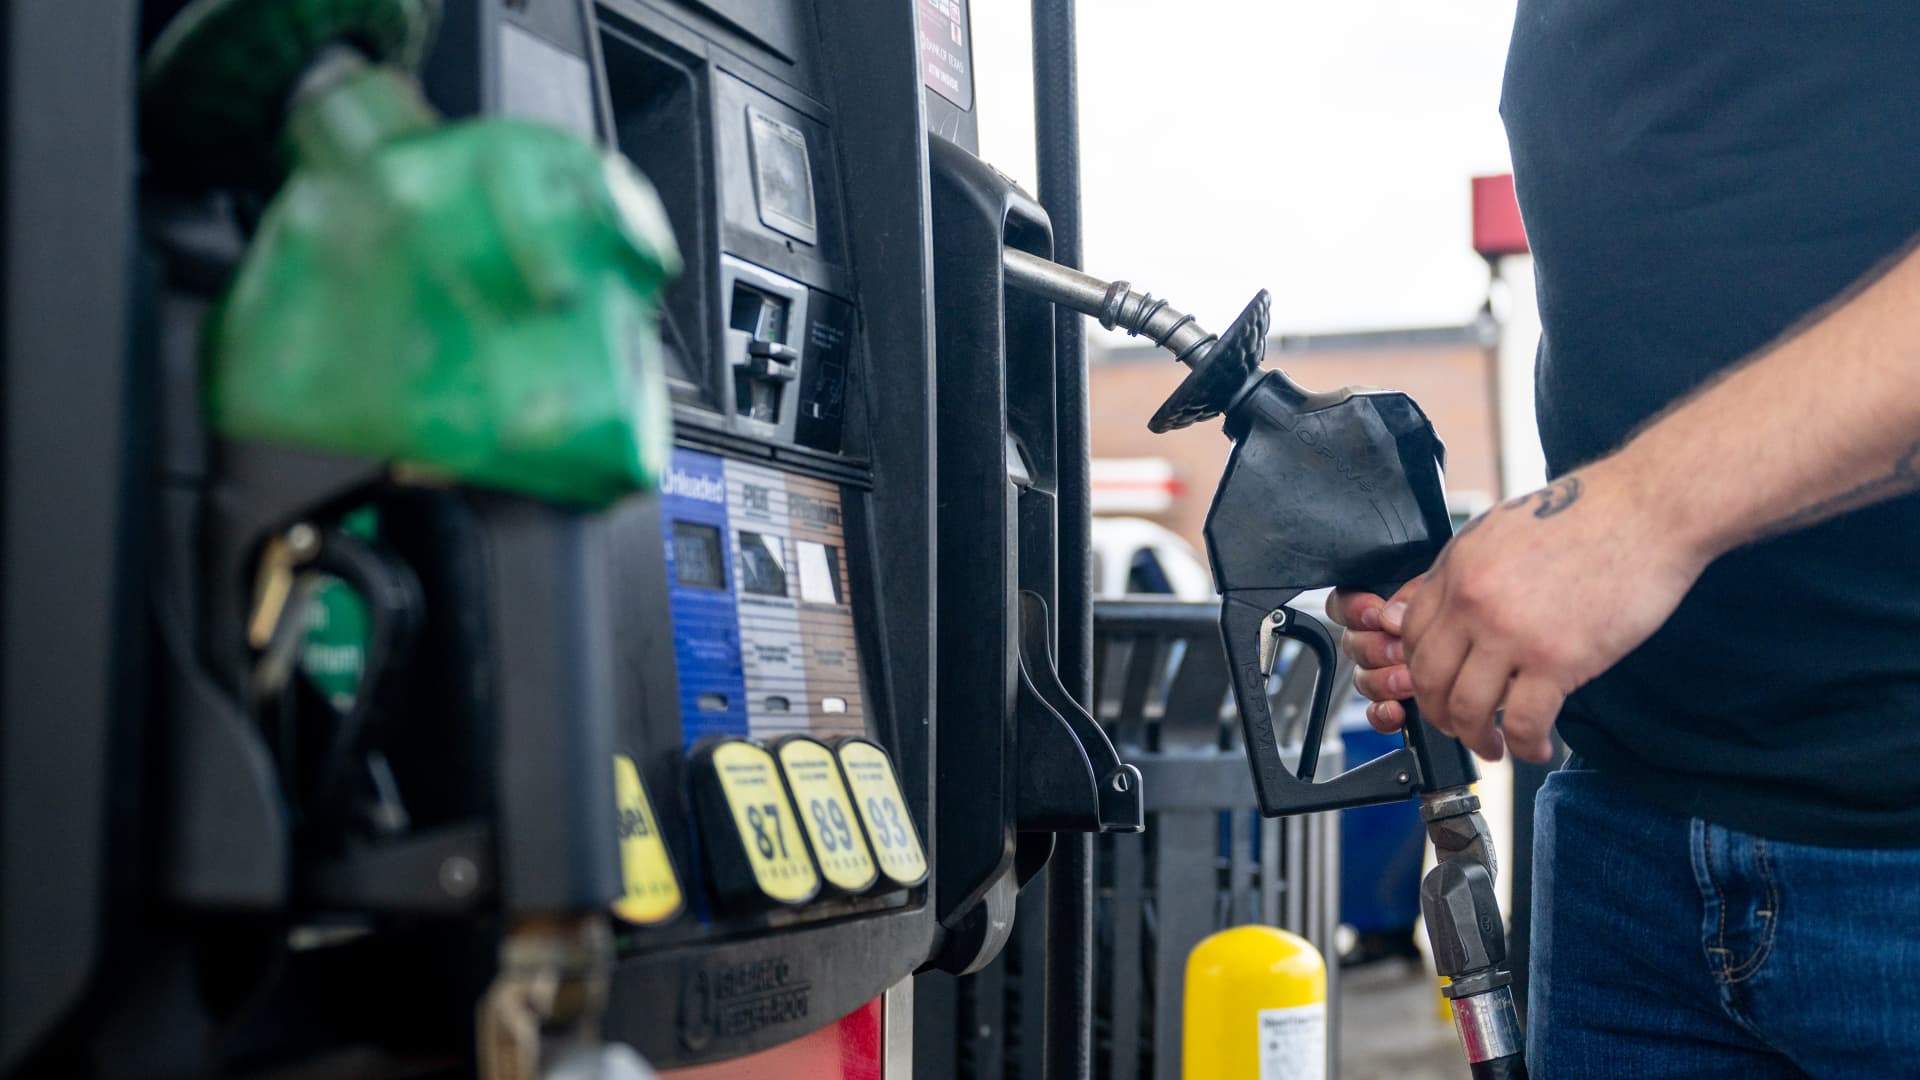
Despite the continuous inflation challenges, consumer spending remains robust. Analysts predict a 0.8% increase in consumer spending for August, which partially correlates with rising gas prices following a modest 0.2% reported increase in July.
Bank of America reports a 6.9% rise in debt and credit card spending year-over-year for the week ending September 19, spurred largely by a significant spike of 26.5% in gasoline prices, underscoring the varying patterns in consumer expenditure. Excluding gas, overall spending climbed by 5.7%.
These persistent inflationary pressures alongside consumers’ willingness to spend provide little grounds for the Fed to conclude that its September rate increase has sufficiently addressed the situation. Consequently, markets are anticipating a high probability of another interest rate adjustment in October, with additional increases anticipated in December or January.
