
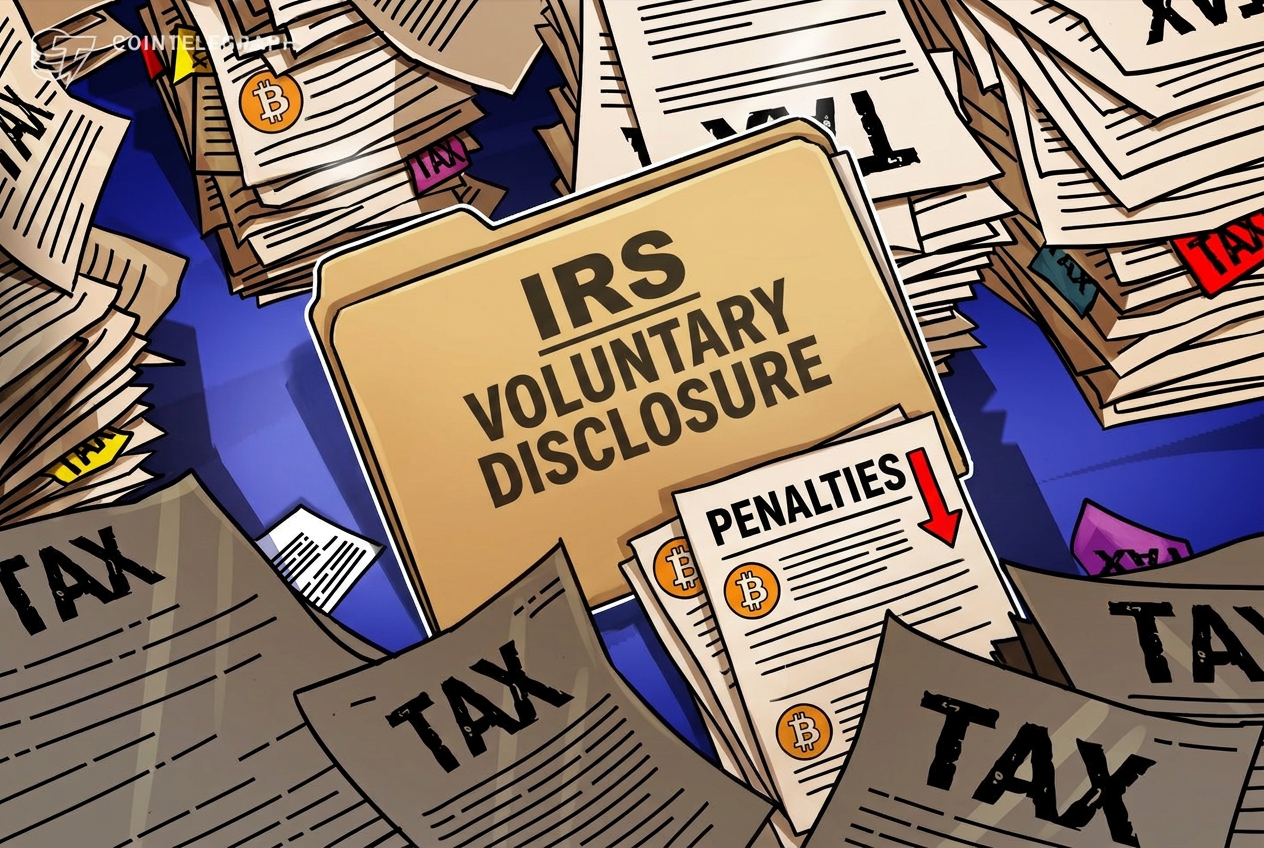
The Internal Revenue Service (IRS) is undertaking a significant reformation of its voluntary disclosure program, specifically targeting tax compliance involving virtual currencies, as reported by Forbes magazine. These changes, which aim to reduce penalties and expedite the resolution of tax violations, are set to be implemented by December 2023.
Key Aspects of the Revised Program
According to IRS Criminal Investigation Director Jarrod Koopman, the enhanced program is engineered to streamline the disclosure process for taxpayers. Once taxpayers submit the necessary documentation, IRS aims to resolve cases within 120 days. Notably, this new approach will not introduce a separate disclosure pathway for digital assets. Instead, cryptocurrency will be incorporated within the existing voluntary disclosure protocol that currently applies to other tax noncompliance forms.
Lower Penalties and Flexible Payment Options
IRS officials have indicated that under the proposed changes, penalties will be substantially decreased compared to the present punitive measures, although specifics were not disclosed. The agency may also provide options for taxpayers to settle outstanding debts via installment plans or offers in compromise, making it easier for individuals to manage their tax liabilities related to virtual currencies.
Transition from Current Process
The planned revisions signify a departure from the present voluntary disclosure framework, which has been criticized for taking over a year to finalize. The existing program focuses mainly on individuals facing potential criminal prosecution for willful tax violations, rather than those who may have inadvertently misstated their tax returns.
Legislative Developments
In parallel, lawmakers are debating a distinct voluntary disclosure initiative aimed at cryptocurrency taxpayers, particularly those who have made unintentional reporting mistakes. The Digital Asset Tax Certainty Act, specifically Section 502, proposes a systematic approach to rectify past infractions, accompanied by clearly defined penalties. This legislation gained traction when it was approved by the House Ways and Means Committee in September.
As these significant changes unfold, cryptocurrency holders and other taxpayers can anticipate a more lenient approach from the IRS towards noncompliance issues, potentially easing the burden on those navigating the complexities of digital asset taxation.
