
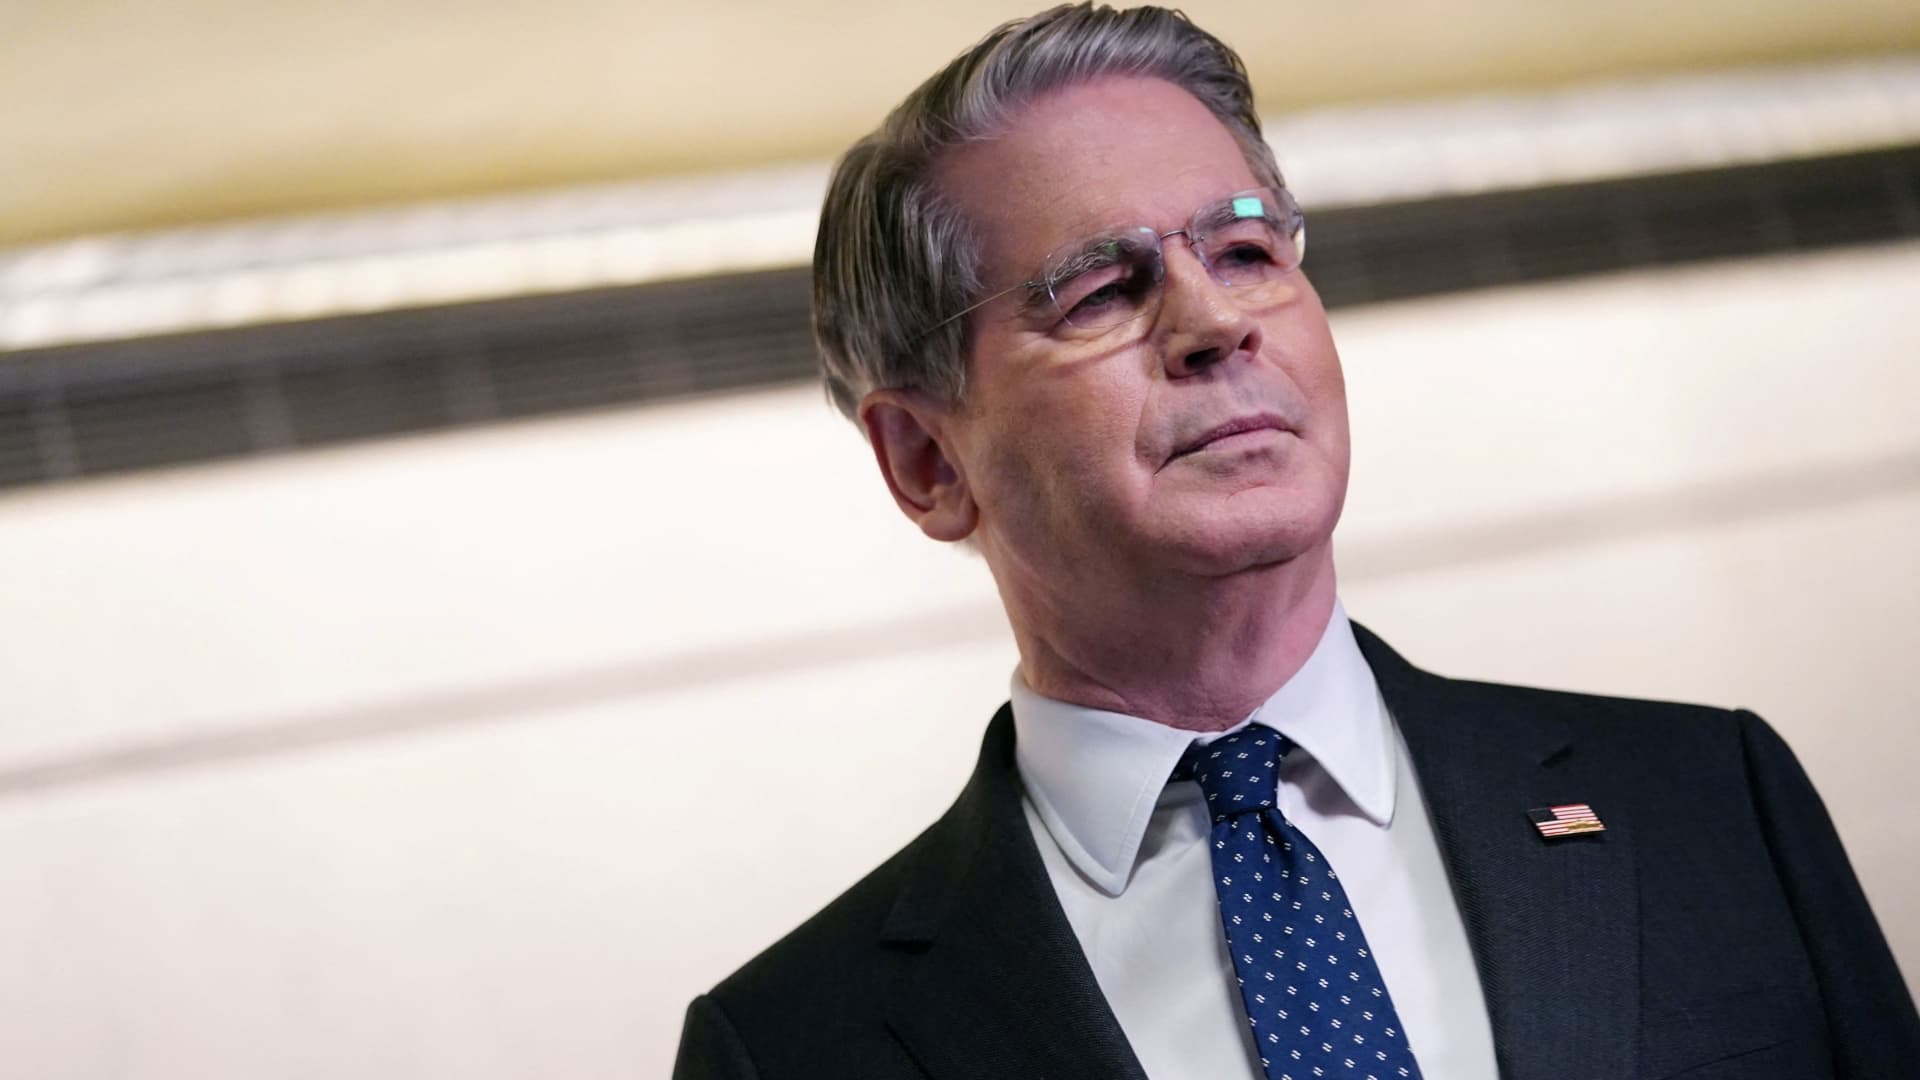
U.S. Treasury Secretary Scott Bessent speaks to the media in Washington, D.C., on September 23, 2026, during a meeting with Chinese Vice Premier He Lifeng.
Nathan Howard | Reuters
Recent surges in U.S. Treasury yields are causing significant concerns for various sectors of the economy, particularly for the government, which carries a debt burden of approximately $40 trillion. This increase is not only poised to escalate borrowing costs for consumers—affecting homeowners and credit card users—but it also offers marginal benefits for banks and limited relief for savers.
The recent uptick in government debt costs can be attributed to several factors, including a new report revealing persistent inflationary pressures, rising expectations for a Federal Reserve interest rate hike in October, and disappointing demand observed during a recent auction of 5-year Treasury notes. Furthermore, intense competition from debt issuance by major corporations has exacerbated these issues.
This week, yields surged sharply—the largest increase in nearly 18 months—marking a continuation of a trend that began in April 2025 when President Donald Trump implemented reciprocal tariffs affecting U.S. trade partners. Despite efforts from Secretary Bessent to enhance market liquidity through heightened buyback activities for longer-term Treasury securities, these initiatives have fallen short of reversing the trend, resulting in rising rates.
The benchmark 10-year Treasury note’s yield recently reached 5.19%, a level not observed since prior to the global financial crisis. Meanwhile, the 2-year note, which is sensitive to Federal Reserve rate expectations, saw its yield surpass 4.9%. This movement reflects traders’ anticipation of additional rate hikes following last week’s increase by the Fed.
Treasury yields
For reference, one basis point is equivalent to 0.01%, and typically, yield fluctuations are inversely related to price changes.
The implications of these movements are particularly critical for consumers, who account for nearly 70% of U.S. economic activity and collectively hold close to $19 trillion in debt. While some savers may experience slightly improved rates on their savings accounts, the relief is unlikely to compensate for the increased costs elsewhere. Dan North, a senior economist with Allianz Trade North America, stated, “The consumer’s the most important part of the economy. They’re going from little tiny yields on savings to ever slightly bigger tiny yields on savings. So I don’t think that really yet helps the consumer that much. But it sure does crush housing, and it [impacts] on all those personal consumer loans, the credit cards and so forth.”

As of now, the interest rate on standard savings accounts hovers around 0.37%, a slight decline since late 2025 when the Federal Reserve implemented three quarterly rate cuts. In contrast, mortgage rates are on a sharply different upward trajectory. The average rate for a 30-year fixed mortgage has risen to 7.26%, an increase of over a quarter percentage point in recent weeks, and nearly a full percentage point in the last year, according to Mortgage News Daily.
Although interest rates on credit cards have remained relatively stable, they are likely to shift if current trends persist.
Understanding the Impact
When the Federal Reserve raises interest rates, the effects ripple through to the prime rate, which serves as a benchmark for adjustable-rate credit. The current prime rate sits at 7%, reflecting a quarter-point increase following last week’s Fed action.
These conditions collectively increase borrowing costs for consumers, potentially leading to reduced demand for loans and credit, which is critical to driving activities within the $32 trillion U.S. economy. North explained, “You raise the fed funds rate, rates in the short term and effectively all along the curve go up. If it makes it harder for somebody to buy a car, then there’s less demand for cars and there’s less demand for auto workers, and the economy slows down. That’s sort of basic economics, but that’s how it works.”
While there may be advantages to higher rates—for instance, banks can potentially profit from higher interest margins—the overall outlook remains cautious. Even bank stock performance has suffered recently, indicating that elevated rates may dampen loan demand and hinder overall economic momentum, which has otherwise shown resilience. The Atlanta Fed is currently projecting GDP growth of 5.1% for the third quarter, contributing to the complex nature of rising yields.

KBW Bank Index, YTD
However, persistent high yields could pose challenges to future economic growth. North warned that smaller and medium-sized enterprises might face the most significant difficulties due to their reduced capacity for borrowing. Limited access to credit can create a challenging environment for these businesses, further complicating the economic landscape.
