
The latest Producer Price Index (PPI) report for September has revealed significant inflationary trends, particularly driven by surging energy costs amid ongoing geopolitical tensions involving Iran. According to the Bureau of Labor Statistics (BLS), the PPI saw an increase of 1.3% for the month, resulting in a year-over-year rise of 6.3%. These figures represent the steepest monthly and annual increases since March and December 2022, respectively.
Economists surveyed by Dow Jones had anticipated a far more modest rise of only 0.6% for September and 5.5% on an annual basis. The dramatic uptick is largely attributed to volatility in the energy sector, particularly in response to decreases in oil supply linked to regional conflicts, which have driven prices significantly higher.
The core PPI, which excludes the often-volatile categories of food and energy, still demonstrated notable growth, climbing 0.7% in September and accumulating a 12-month increase of 5%. This data further indicates that the inflationary pressures are broadening, as nearly half of the increase in processed goods for immediate consumption was connected to rising diesel fuel prices, underscoring the cascading effects of energy costs on other categories.
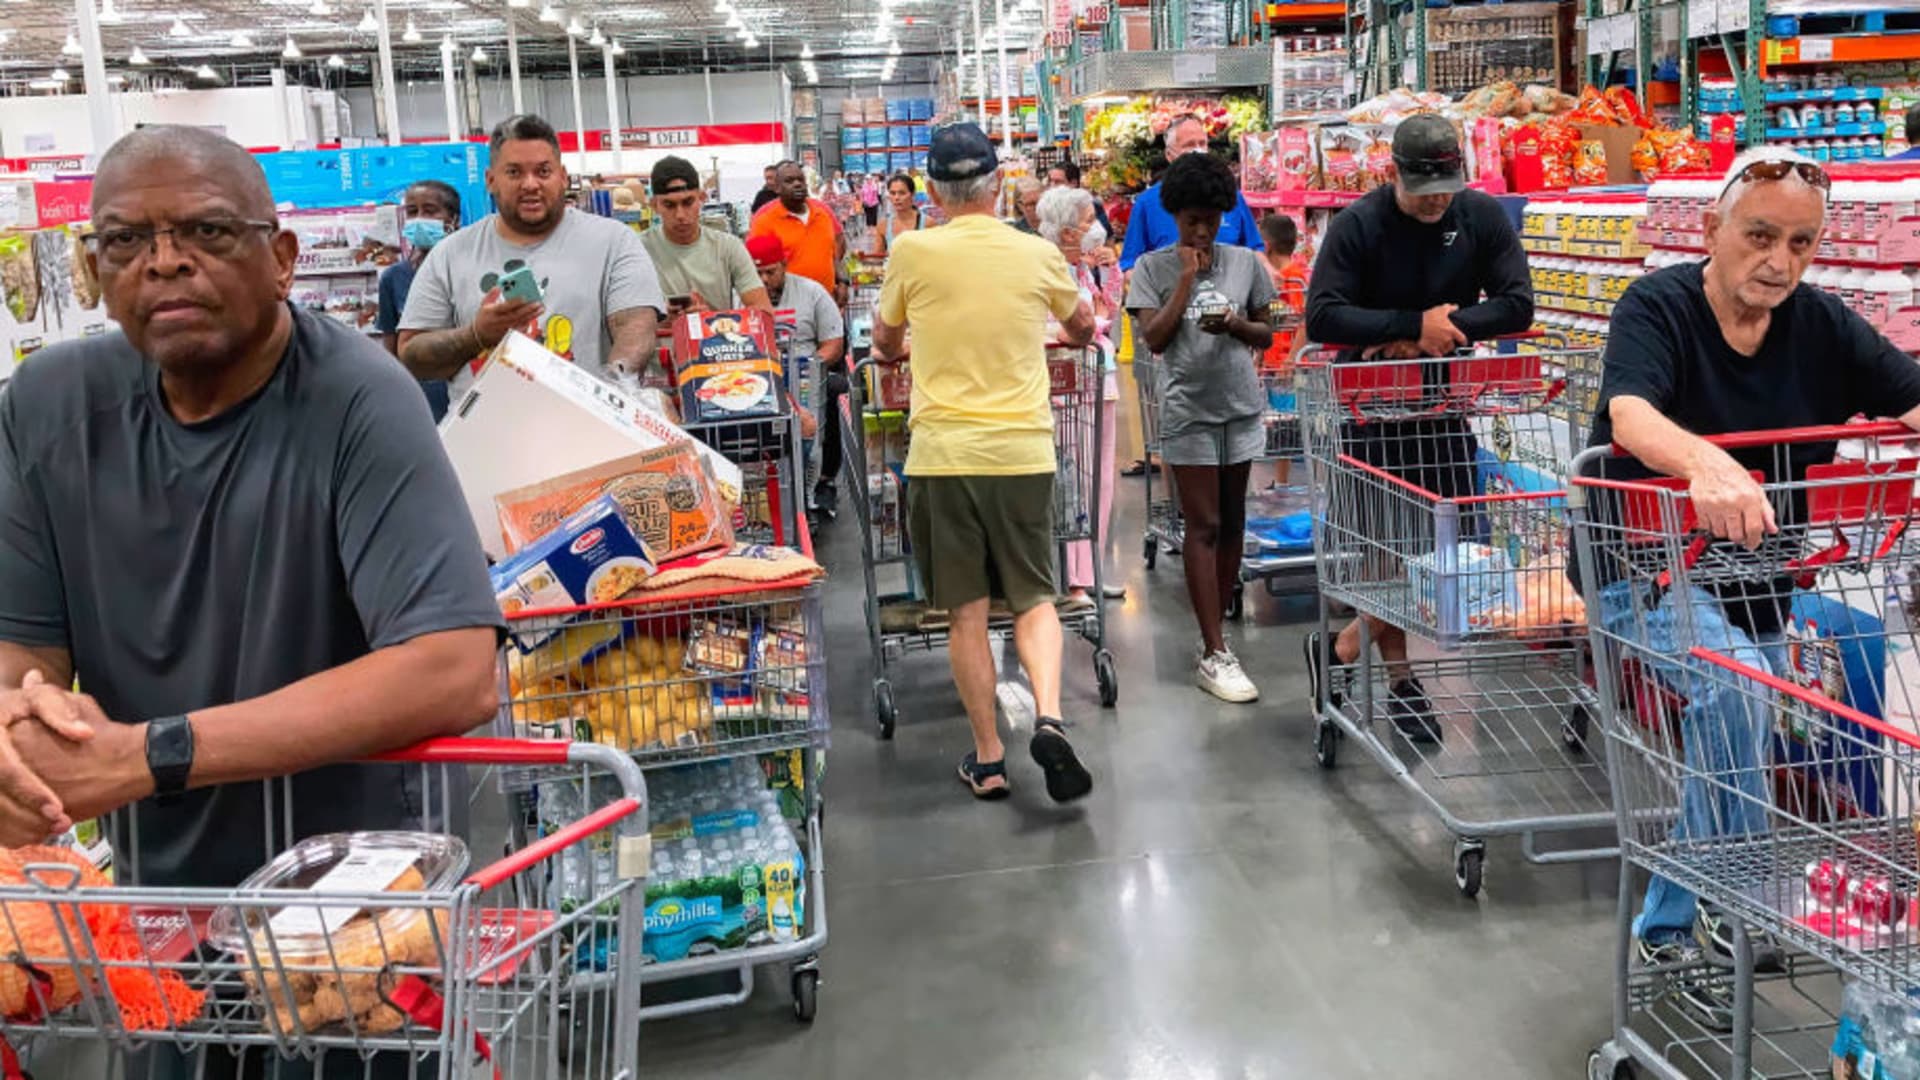
Recent economic indicators suggest consumers and businesses alike are feeling the pinch of rising inflation. The Consumer Price Index (CPI) report released Wednesday showed a 0.6% rise from August to September and a year-over-year increase of 3.7%, slightly above the 3.6% forecast. The core CPI, which excludes food and energy prices, increased by 0.3% month-over-month and 2.6% annually, again surpassing economists’ predictions.
Adding to this trend, the Federal Reserve’s latest Beige Book report indicated a significant rise in mentions of inflation-related terms, indicating heightened concern about price stability across various sectors. This reflects the growing narrative that inflation remains persistent and influential within the economy.
In terms of consumer spending, retail sales increased by 0.8% in September, outperforming analysts’ projections of 0.4%. However, this marks a noticeable slowdown from the previous month, which witnessed a retail sales rise of over 1%. Excluding vehicles and fuel expenditures, retail sales saw a more modest increase of 0.25%, down from around 1.1%, highlighting how rising fuel prices may be constraining consumer spending in other areas.
The recent data has prompted a shift in market expectations surrounding potential interest rate adjustments by the Federal Reserve. Current traders now estimate a nearly 34% chance of a rate hike during the Fed’s October meeting, a significant rise from just under 18% the week before. Furthermore, approximately 90% of traders expect at least one rate increase by year-end.
As Chris Zaccarelli, Chief Investment Officer at Northlight Asset Management, noted, “With a second day in a row of higher-than-expected inflation numbers, it seems the Fed will have no choice but to raise rates again this year.” These inflationary trends and their impact on the economy come at a critical time, offering insights just ahead of the midterm elections in the U.S., which may influence the political landscape moving forward.
