
Long-term bond yields in the U.S. have surpassed 5%, coinciding with a staggering federal deficit projected to reach $2 trillion. These indicators are providing citizens a glimpse into the potential realities of a U.S. debt crisis—one that could drastically impact the economy if left unaddressed. As the upcoming midterm elections are likely to result in a divided government, the path toward addressing these fiscal challenges remains uncertain.
The ramifications of higher interest rates, exacerbated by significant federal debt issuance, are beginning to affect various sectors of the economy while simultaneously worsening the government’s debt situation. With political cooperation on fiscal matters appearing unlikely in the wake of the November 3 elections, any viable solutions to the downturn could be years away.
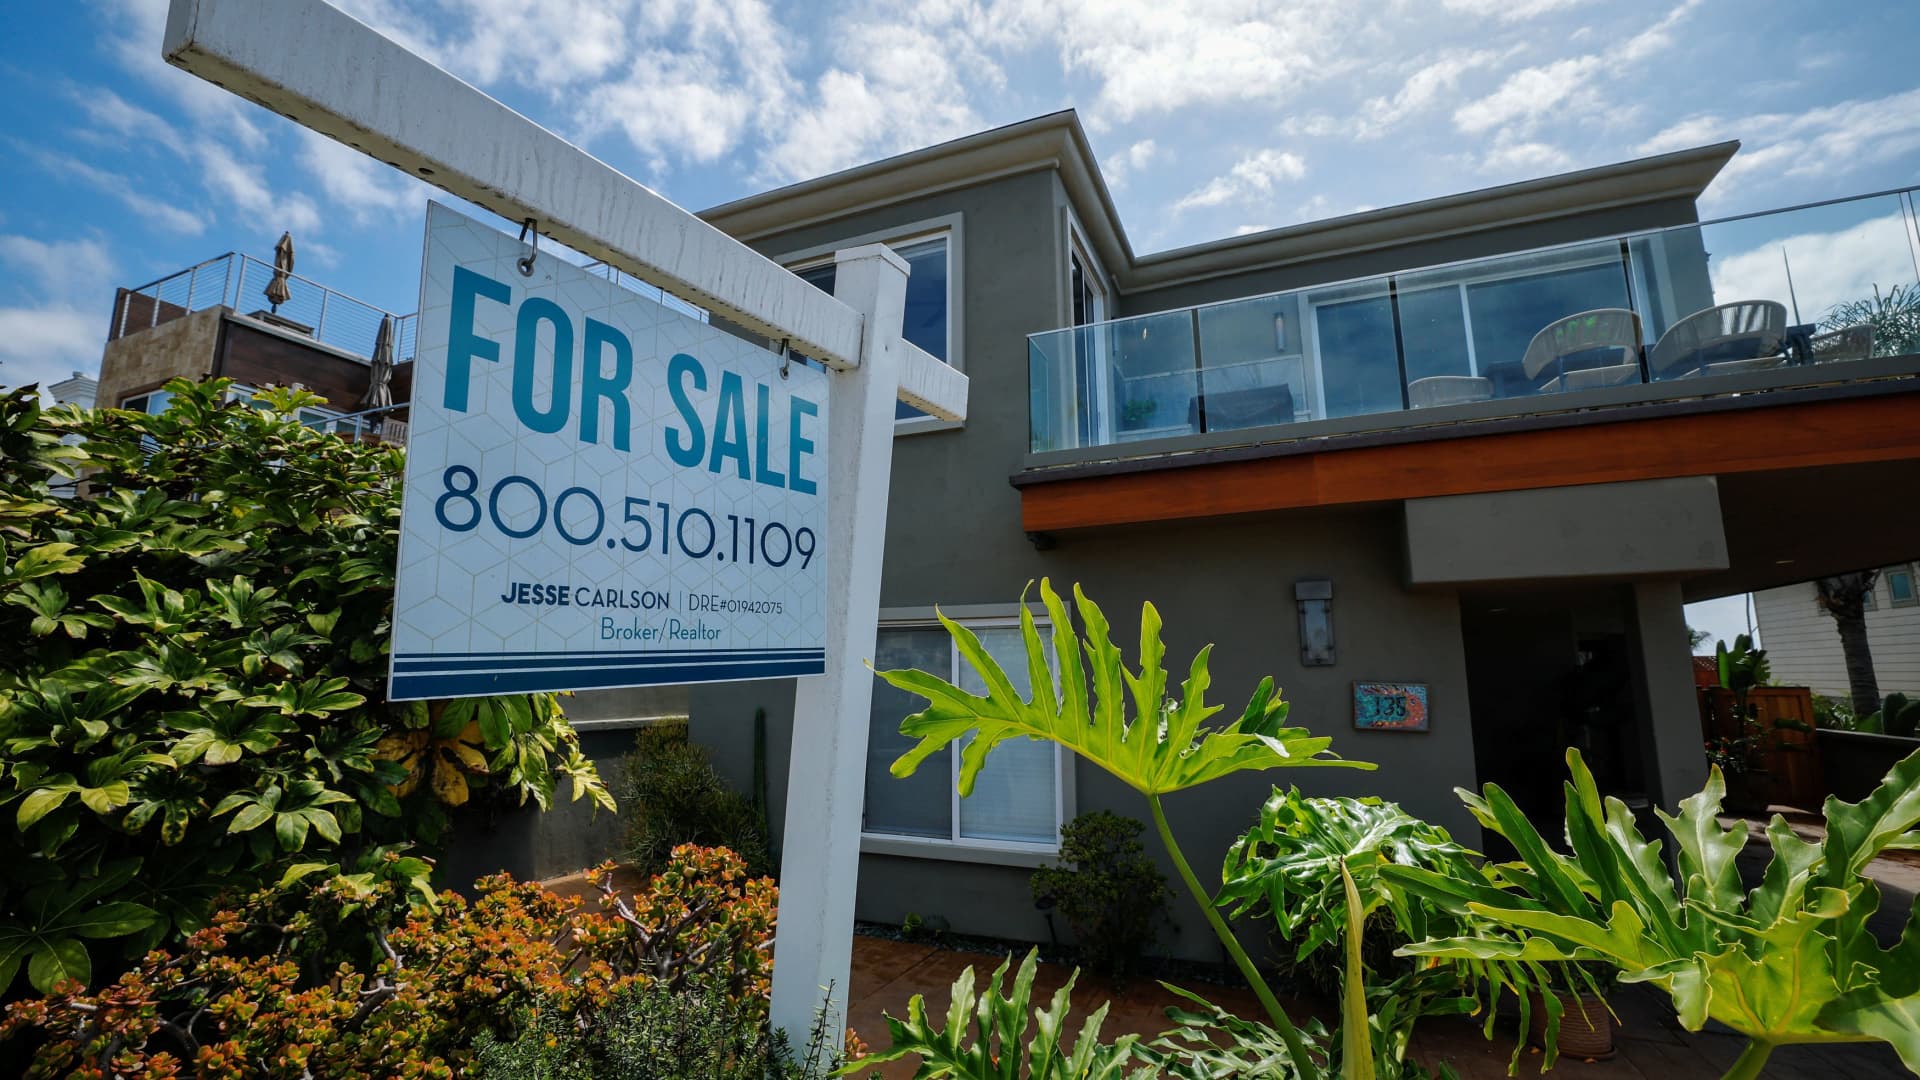
The housing market is already feeling the strain, as evidenced by a 4% decline in pending home sales for September, which Redfin reported as the most notable monthly decrease in three years. This downturn aligns with the rise in the average 30-year fixed-rate mortgage, which currently hovers around 7.5%. Mortgage rates are closely tied to the yield on the 10-year Treasury note, which has surged 123 basis points since late February and closed recently at 5.19%.
Several factors are contributing to the increasing yield on the 10-year Treasury. The ongoing conflict with Iran, ignited on February 28, has driven up oil and diesel prices, leading bond traders to demand higher yields as a buffer against anticipated interest rate hikes by central banks, including the Federal Reserve. Investors are seeking greater returns for holding longer-term bonds, especially since the U.S. government is likely to continue saturating the market with debt. This intense competition for capital is being fueled by corporate entities issuing substantial amounts of new debt to support infrastructure developments in artificial intelligence.
A credible commitment from the U.S. government to reduce the deficit could potentially moderate long-term bond yields. However, the extent of this effect remains uncertain and would depend on the size of any deficit reduction, as well as external conditions like a slowing economy or declining oil prices. Treasury Secretary Scott Bessent has suggested that aiming for a deficit below 4% of gross domestic product by the end of President Donald Trump’s term could facilitate this virtuous cycle of reduced deficits and lower yields.
Despite these aspirations, achieving such a target appears improbable. Preliminary indications predict that the deficit for the fiscal year 2026, which concluded in September, will be near or above the anticipated $2 trillion mark. This forecast suggests that the deficit may be between 6.0% and 6.2% of GDP for the year, according to the Congressional Budget Office (CBO), which estimates a deficit of $1.993 trillion based on third-quarter GDP projections.
The challenge of reducing debt is compounded by higher interest rates. Should rates exceed CBO expectations by half a percentage point, the total deficit over the next decade could increase by $1.9 trillion, while a rise of 1.5 percentage points could escalate it by as much as $6 trillion. The CBO has estimated that the 10-year Treasury yield will average 4.3% over the next ten years, significantly lower than the current rate of 5.3%. Prolonged elevated rates would necessitate substantial and sustained growth to manage the existing levels of debt.
“My view is that we’ve got this mountain of debt, and we have to grow our way out of it,” Bessent noted in Dallas last month, highlighting the potential of artificial intelligence as a critical growth driver.
While advancements in AI could aid in economic growth, they cannot single-handedly resolve the debt predicament. According to the Committee for a Responsible Federal Budget, achieving a balanced budget solely through growth would require a decade of sustained expansion at 7.2%—a feat deemed highly challenging. Recent adjustments have indicated that GDP growth was revised from 1.5% to 2.2% annually for the second quarter, emphasizing the extraordinary efforts needed to reach the targeted growth rate.
As President Trump approaches the concluding two years of his term—often a period associated with significant legislative endeavors—he has not demonstrated a strong inclination to prioritize deficit reduction. His recent pledge to distribute $5,000 checks to all adult Americans if Republicans win the elections underscores this point.
Political analysts predict that Republicans are likely to lose at least one, if not both, chambers of Congress in upcoming elections. While divided government can sometimes yield unexpected bipartisan compromises, the substantial differences in starting positions—particularly regarding issues like reversing the $1 trillion in healthcare cuts implemented last year—make collaboration difficult. Rep. Hakeem Jeffries, who is poised to become the next House speaker for the Democrats, is focused on counteracting those cuts.
With the total U.S. debt reaching $40 trillion this year, questions surrounding sustainability become ever more pressing. A severe debt crisis could occur further down the line, characterized by dramatically increased debt yields and a significant sell-off of dollar assets by global investors, leaving the Treasury and the Federal Reserve with limited options for intervention.
For the time being, while higher bond yields are attracting some investors to U.S. government bonds, they serve as a reminder that elevated borrowing costs do not equate to a crisis. Nonetheless, it is clear that economic solutions alone will not suffice to avert a substantial debt crisis. A renewed political commitment is essential to effectively address these fiscal challenges.
