
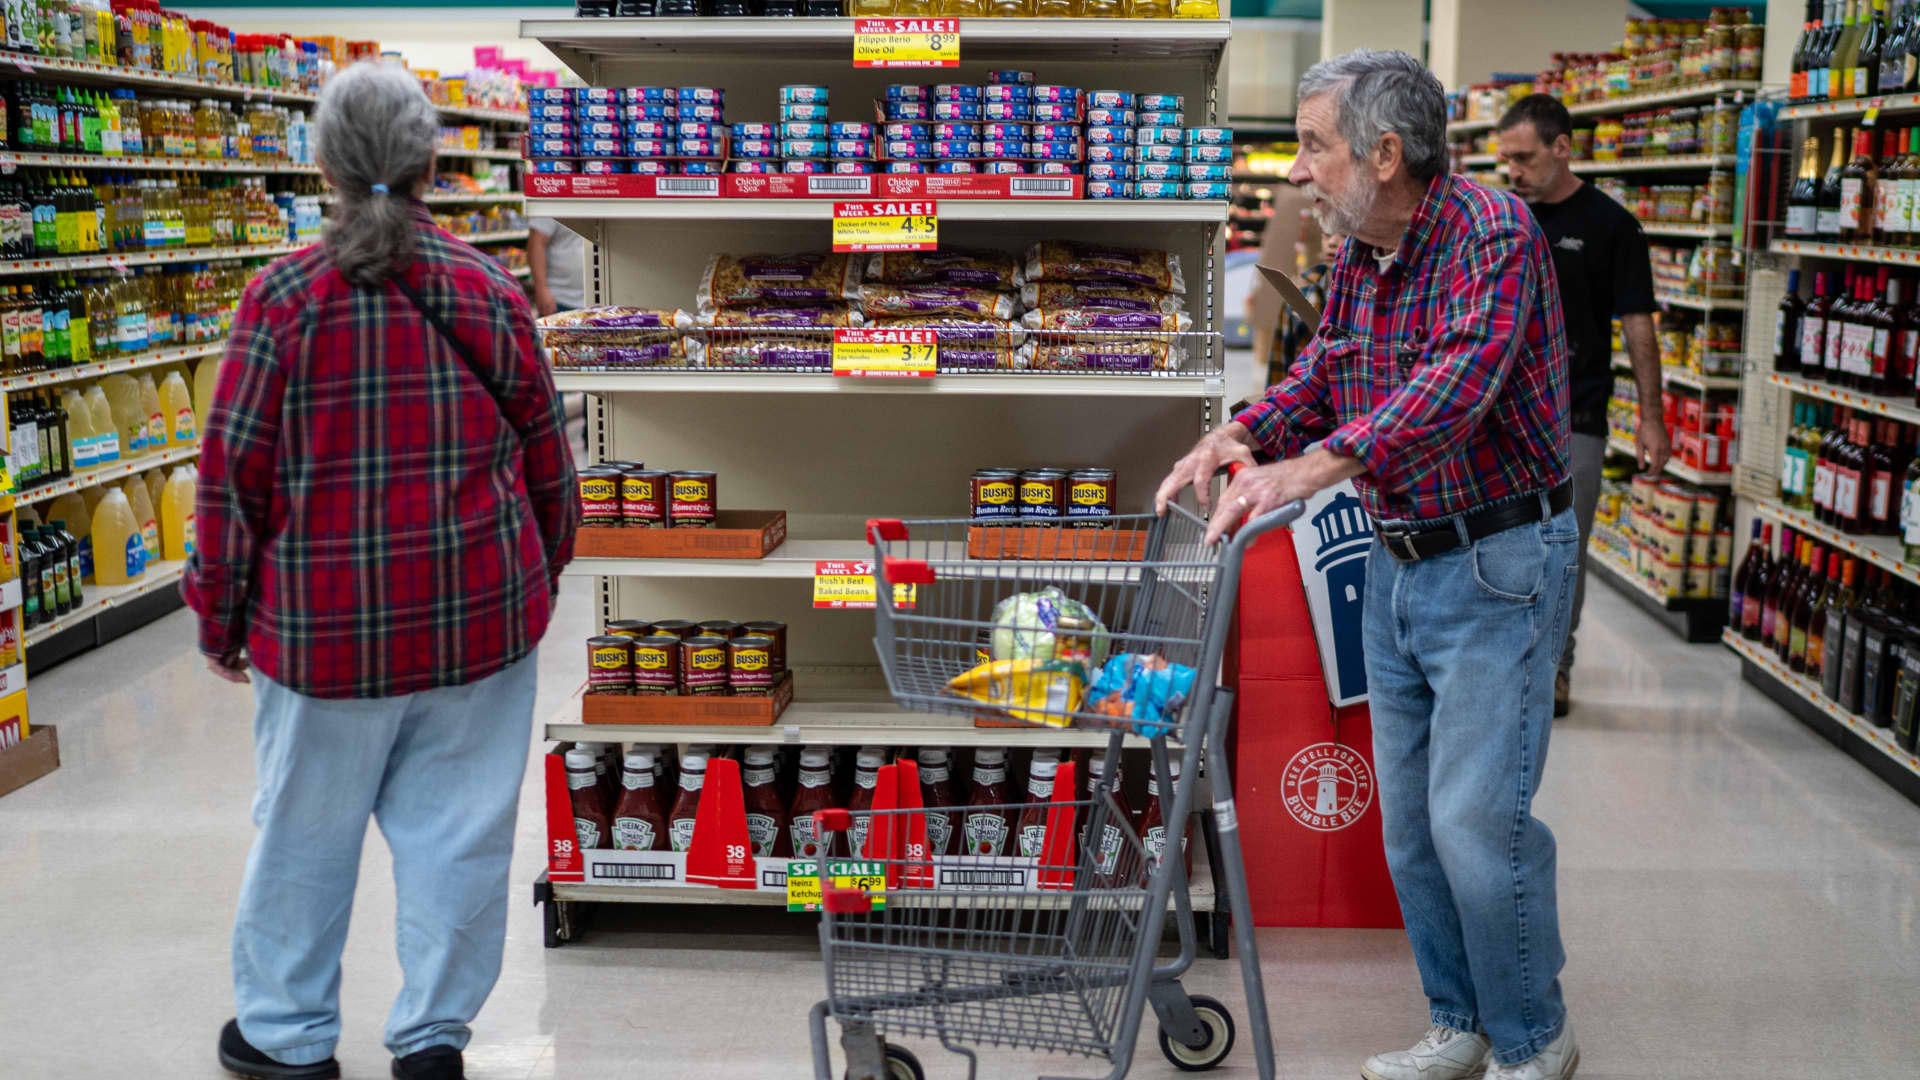
The latest report from the Bureau of Labor Statistics reveals that consumer prices in the U.S. are continuing to rise, resulting in an inflation rate that remains above the Federal Reserve’s target. In September, the consumer price index (CPI), which reflects the cost of a wide array of goods and services, increased by a seasonally adjusted 0.6%. This brings the year-over-year inflation rate to 3.7%, surpassing economists’ expectations of 0.6% and 3.6%, respectively.
When excluding the often-volatile categories of food and energy, the core CPI rose by 0.3% in September, indicating a 2.6% increase on an annual basis. These figures also exceeded analysts’ anticipations, which had estimated a rise of 0.2% monthly and 2.5% annually. The previous month’s inflation rates stood at 3.4% for the overall index and 2.4% for the core measure.
Driving the inflation surge is a significant jump in energy costs. The energy index alone increased by 5.2%, largely influenced by ongoing geopolitical tensions, particularly between the U.S. and Iran. Fuel prices, especially gasoline, played a substantial role; gasoline prices soared by 9.1%, accounting for roughly half of the overall CPI increase. Over the past year, gasoline prices have risen by 34.2%, while fuel oil has seen an astounding increase of 74.2%.
In contrast, food prices remained stable over the month, experiencing a modest annual increase of 2.5%. Additional cost increases were observed in shelter (up 0.4%), and used car and truck prices, which rose by 0.7%. Apparel prices, sensitive to trade tariffs, also saw a rise of 0.3%, with an annual increase of 3.4%.
Following the release of the CPI data, stock market futures turned negative, while bond yields rose sharply. An increased likelihood of a rate hike was reflected in futures trading, with expectations for a potential increase when the Federal Open Market Committee meets on October 27-28. Analysts estimate about a 54% chance of a rate hike at this meeting, with odds exceeding 96% for an increase before the year’s end, and a near even chance of a half-percentage point hike by December.
“CPI came in hot and it wasn’t just fuel prices, as core inflation ran at a 3.7% annualized pace in September and 3.2% over three years,” said Sonu Varghese, chief macro strategist at Carson Group. His remarks underscore the persistent and broad-based nature of inflation, which has surprised many investors. The impact of rising diesel prices and increasing demand associated with technological advancements in artificial intelligence has yet to be fully realized in these metrics.
The Federal Reserve’s inflation target of 2% has not been met since March 2021, with inflation rates fluctuating significantly since early 2026. The CPI has shown signs of a downward trend but remains elevated, particularly in the wake of geopolitical tensions and supply chain disruptions stemming from tariffs and heightened demand from AI-related sectors.
In response to these inflationary pressures, the Federal Reserve raised interest rates for the first time in over three years in September, implementing a quarter-point increase that brought the benchmark funds rate within the range of 3.75%-4%. Market analysts predict the Fed may opt for a pause on rate hikes in October while anticipating further increase before the end of the year.
Although the factors contributing to the energy price surge are often seen as temporary, the Federal Reserve is concerned that prolonged conflicts could embed these price increases into broader economic expectations. Analysts also note that in addition to energy volatility, tariffs imposed during former President Trump’s administration and heightened demand due to advancements in artificial intelligence continue to exert upward pressure on prices.
While key Fed officials exhibit cautious optimism about the need for immediate hikes, expectations remain that further rate increases are likely this year, with projections suggesting at least two more hikes could occur in 2027. It is important to note that while the CPI is a valuable indicator of inflation trends, the Federal Reserve primarily relies on the personal consumption expenditures price index from the Commerce Department for its future predictions and policy decisions, with the latest PCE data set to be released later this month.
